There’s a number that gets quoted everywhere for a comfortable retirement in Australia.
It’s worth knowing. It’s also worth questioning, because when you dig into what that “comfortable” actually buys, it’s a long way from the retirement most people have in mind.
In this post we’ll look at what the official benchmark says, what its version of comfortable really includes, why I think the real target is higher, and how to work toward the retirement you actually want rather than the one someone else has decided is enough.
What the Benchmark Says
The most quoted figure in Australia comes from the ASFA Retirement Standard. It estimates what retirees spend to live either a “modest” or a “comfortable” lifestyle, and it’s updated every few months.
As of 2026, here’s what ASFA says you need each year for a comfortable retirement, assuming you own your home.
- Comfortable, single – about $56,166 a year
- Comfortable, couple – about $78,998 a year
To fund that, ASFA estimates you need roughly $630,000 in super as a single, or $730,000 as a couple, by the time you retire at 67. That’s lower than the scary “$1,000,000” figure you often hear, because the Age Pension tops up the rest.
So far, so reassuring. But this is where I’d pump the brakes.
The Problem With “Comfortable”
Here’s what that comfortable budget is quietly built on, once you read the fine print.
It assumes you own your home outright, with no rent and no mortgage. It assumes you’ll draw your super all the way down to zero by around age 92, leaving nothing behind. And the travel budget inside it is modest – enough for a domestic trip a year and the occasional small overseas one.
For a lot of people, that’s not the retirement they’re picturing.
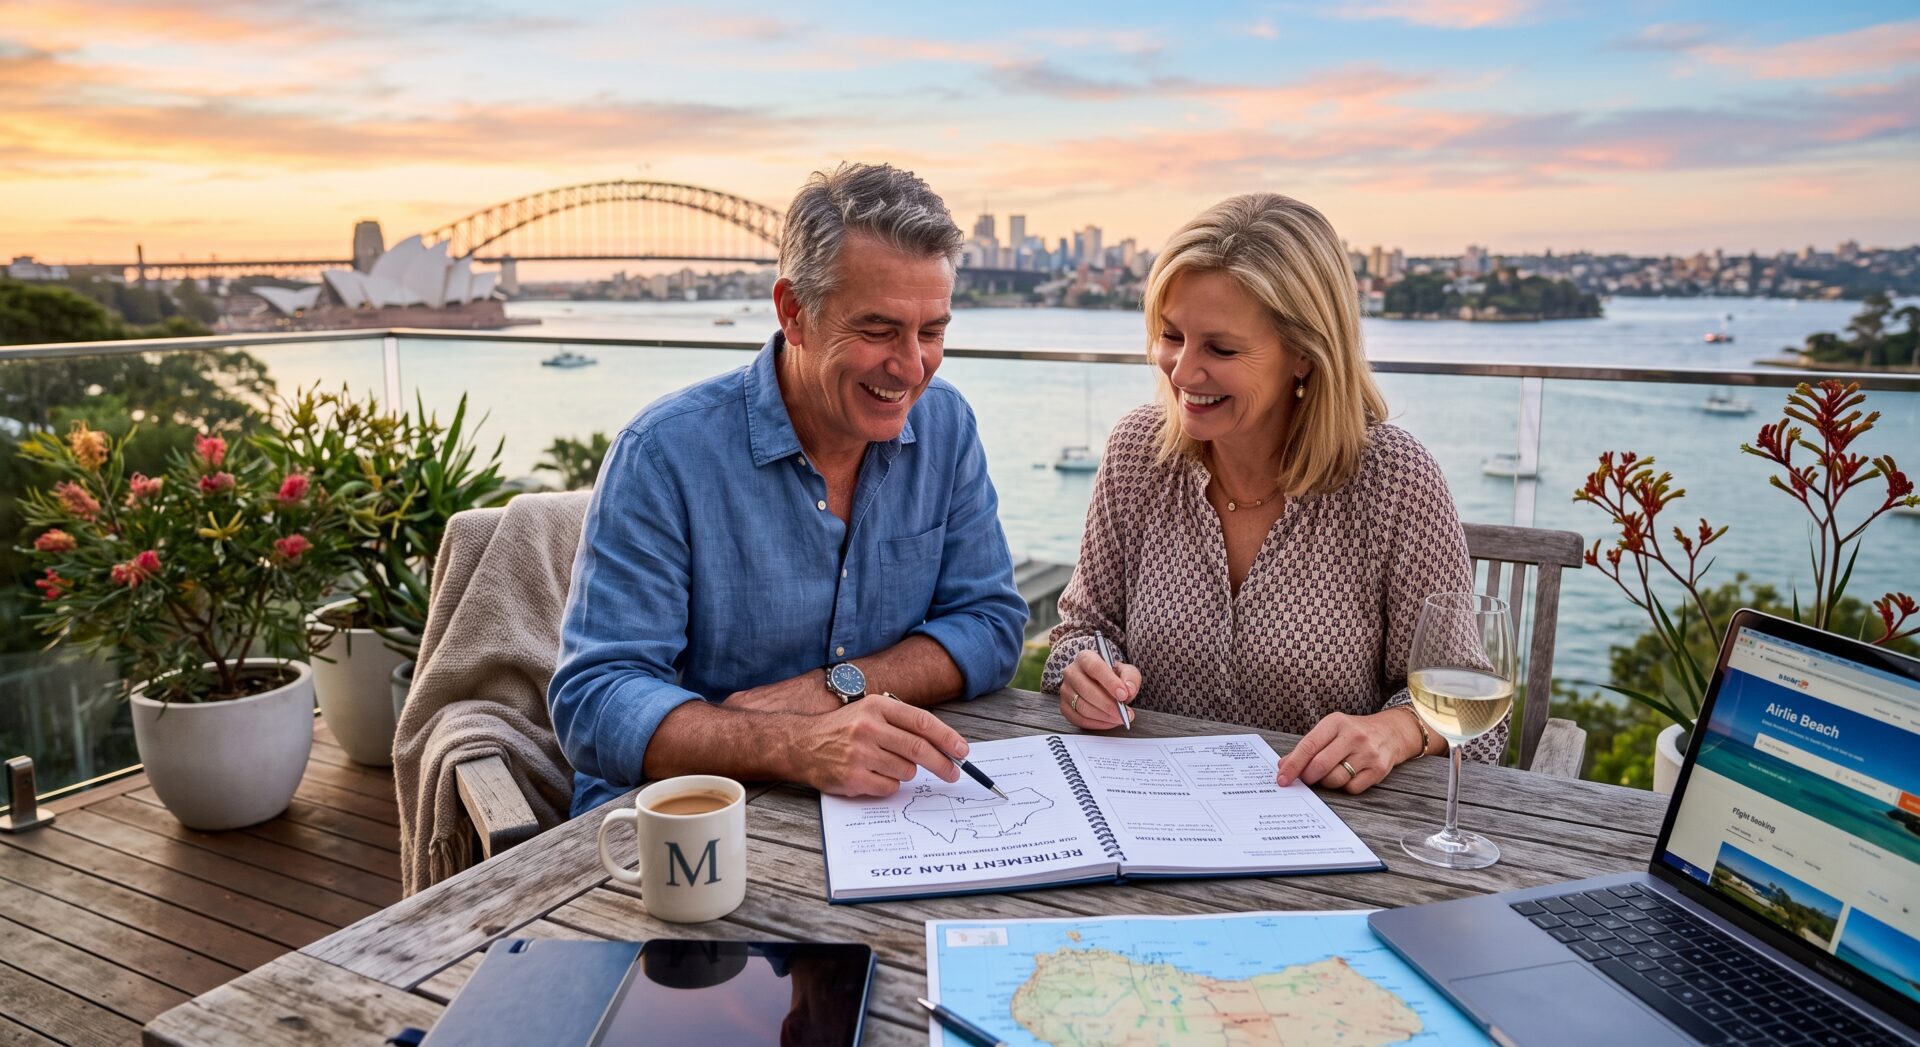
When most people imagine a comfortable retirement, they picture real travel – overseas trips with some trimmings, the longer trips they put off during their working years, the freedom to say yes without checking the balance first. They picture helping the kids with a deposit. They picture not having to track every dollar at exactly the age they hoped to stop worrying about money.
The ASFA figure doesn’t stretch to much of that. It’s a careful, modest definition of comfortable, and that’s great to know as a baseline. I just don’t think it should be your goal. It’s the floor, not the ceiling.
Why I Think the Real Target Is Higher
For the retirement most people actually want, I think a target north of $1,000,000 is a far better number to aim at than the benchmark.
That’s my view, not a rule, and the right figure always depends on your situation. But here’s the thinking behind it.
A bigger pot buys three things the benchmark skips. It buys genuine choice – the ability to travel properly, help family, and handle a surprise without it derailing you. It buys independence from the Age Pension, so your retirement rests on what you built rather than on government policy that can change. And it buys the option to stop earlier, or leave something behind, instead of a plan that only works if you spend your very last dollar in your early 90s.
None of that is about being greedy. It’s about aiming for the life you want, rather than the one a benchmark has decided is acceptable. In my experience, people rarely regret aiming a little higher here.
And about that reassuring statistic you’ll see quoted – that many retired couples spend around $55,000 a year. It’s true. But it’s worth asking whether that’s the life they chose, or the life their savings allowed. Often it’s the second. I’d rather help you build the first.
Isn’t Aiming for More Than a Million Unrealistic?
For most people, no – and this is the part worth sitting with, because it’s where the fear usually is.
A million dollars sounds enormous when you look at it as one lump. But it isn’t built in one lump. It’s built the same way all wealth is – a decent savings rate, invested consistently, compounding over years, with super doing a lot of the quiet work in the background through your working life.
Someone who takes control of their money management, lifts how much they keep each year, and puts it to work across more than one asset class can get there far more often than they’d expect. Time is the real engine, which is why the best day to start was years ago, and the second best is today.
So this isn’t a reason to feel behind. It’s a reason to aim at the right target and give yourself the runway to reach it.
How to Work Toward Your Number
You don’t need a finance degree to get a rough figure. Here’s a simple way to think about it.
Start with the retirement you actually want, not the one the benchmark allows. Picture the travel, the lifestyle, the help you’d like to give – then put a realistic annual cost on it. That number is the thing everything else hangs off.
From there, the job is to close the gap between where you are and where you want to be. Lift your savings rate, build wealth across more than one asset class, top up super where it suits you, and build some streams of passive income so your money isn’t relying on you alone. If you want to work backwards from independence at any age rather than traditional retirement, my guide on financial independence walks through that version of the sum, and if you’re drawn to stopping well before 67, that’s the world of choosing to retire early.
For the specifics – how much pension you might receive, the tax side, the right contribution strategy – this is genuinely worth getting advice on. The rules are detailed and they change.
In Summary
The official benchmark says a comfortable retirement in Australia costs a single person about $56,166 a year and a couple about $78,998, funded by roughly $630,000 to $730,000 in super. It’s a useful floor to know.
But their “comfortable” assumes your home is paid off, your travel is modest, and your super runs out in your early 90s. For the retirement most people actually picture, I think a target above $1,000,000 is the better goal – not to feel behind, but to aim at real choice.
Start with the life you want, put a number on it, and build toward that. The benchmark is someone else’s definition of enough. Yours is the one that matters.
What does your ideal retirement actually look like – and is it bigger than “comfortable”?
P.S. Whatever number you’re aiming at, it starts with knowing what you spend now. Grab my free Wealth Tracker to see where your money goes – it’s the first step to building the retirement you actually want.