Quick question before we start.
Would you rather have $1,000,000 handed to you right now, or a single cent that doubles every day for 30 days?
Most people grab the million. It’s the wrong call. That doubling cent grows to more than $5,000,000 by day 30 – and the way it gets there is the most important idea in all of investing.
That idea is compound interest. In this post we’ll look at what it actually is, why it’s so ridiculously powerful, why it’s not the special bank account most people think it is, and how you can put it to work from wherever you’re starting.
What Is Compound Interest?
Compound interest is simply earning returns on your returns.
To see it, picture the alternative first. Simple interest is when you earn a return only on the money you originally put in. Put in $1,000 at 10% and you earn $100 a year, every year, forever. Steady, but flat.
Compound interest is different, and better. You earn your return, then next time you earn a return on the original amount plus the return you already made. Your $1,000 earns $100, so now you’ve got $1,100. The next year’s 10% is calculated on $1,100, not $1,000 – so you earn $110. The year after, more again.
Each round, the base gets a little bigger, so each return gets a little bigger. It’s a snowball rolling downhill, picking up more snow the further it goes. That’s the whole secret, and it’s why compounding is sometimes called the eighth wonder of the world.
Why Compound Interest Is So Powerful
Here’s the part that trips everyone up, and it’s exactly why people grab the million dollars instead of the doubling cent.
Compounding is slow, right up until it’s astonishing.
Go back to our penny. For the first stretch, it looks pathetic. By day 10 you’ve got about $5. By day 15, around $164. Even on day 20, after two thirds of the time has passed, you’re sitting on just $5,243. You’d be forgiven for feeling ripped off.
Then it detonates. Day 25, you’re at $167,772. Day 29, over $2,600,000. Day 30, more than $5,300,000.
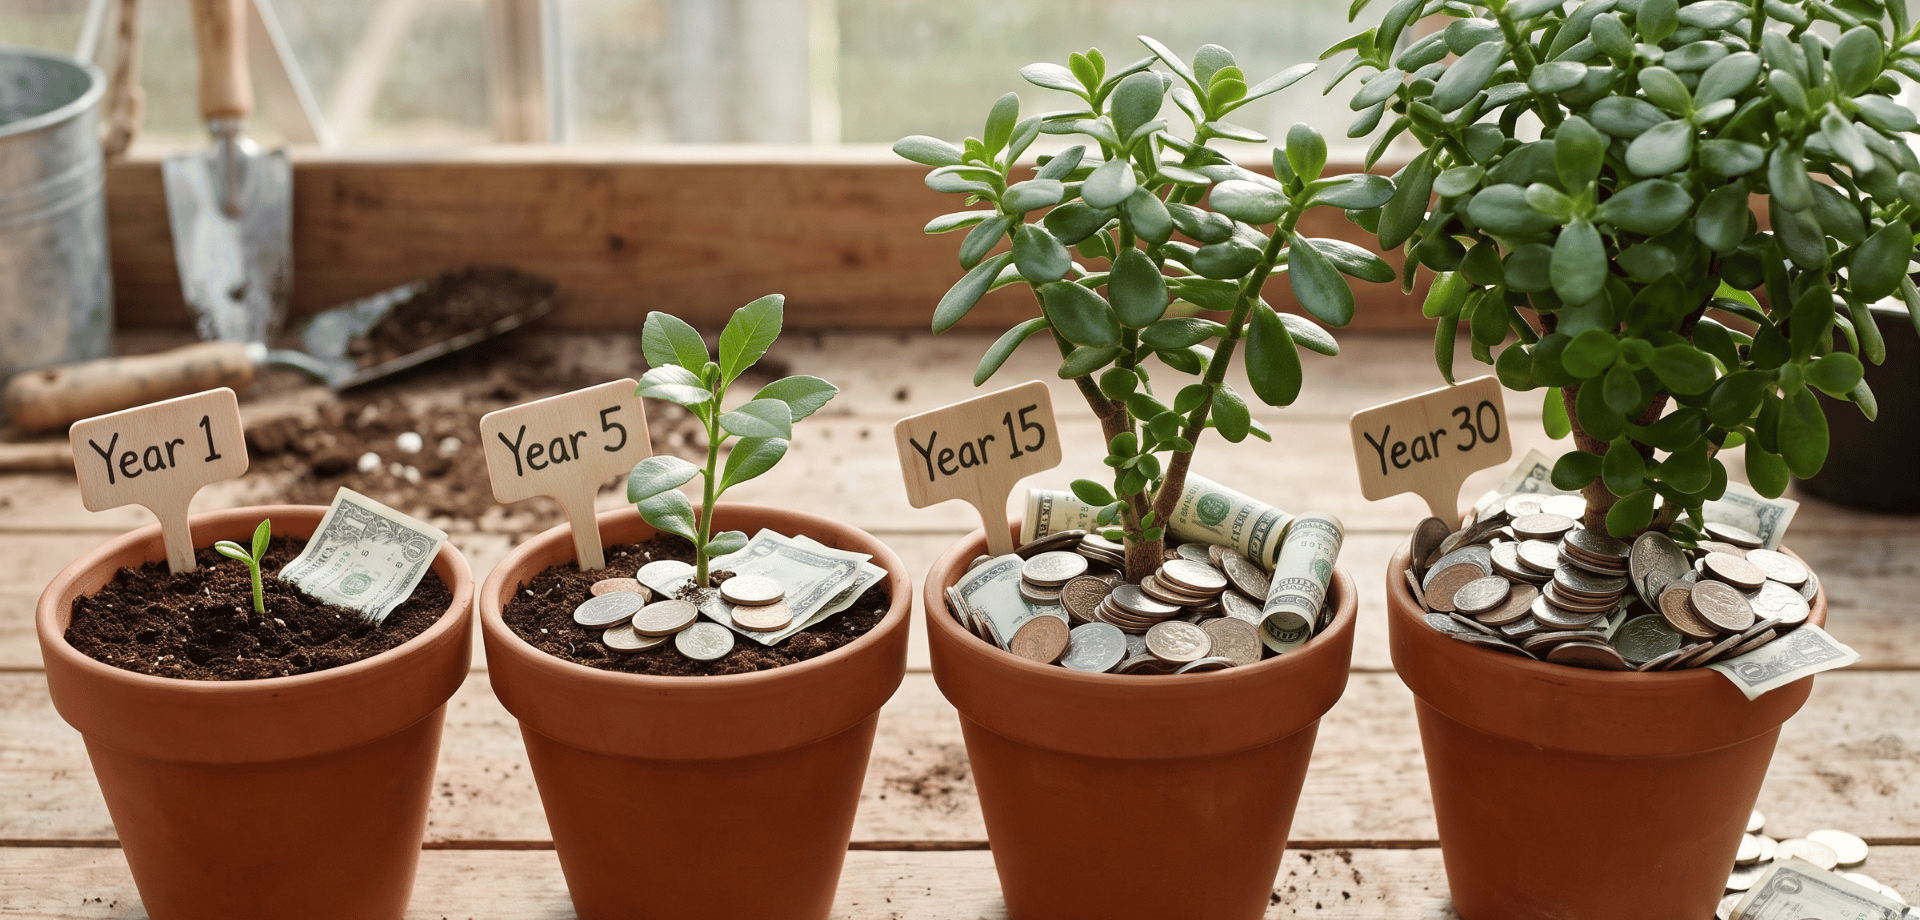
The growth was there the whole time, quietly working. It just does most of its heavy lifting right at the end. That’s the shape of compounding – a long flat stretch, then a curve that shoots for the sky. Most people quit during the flat bit, never seeing the payoff that was coming.
Why Starting Early Beats Starting Big
Because compounding rewards time more than anything else, when you start matters more than how much you start with. Let me show you with two people.
Say two friends each invest $500 a month and earn a 7% average return a year. This is just an illustration, not a promise – real returns bounce around and are never guaranteed.
The first starts at 25 and stops adding at 65. The second waits, starts at 35, and also stops at 65.
By 65, the early starter has around $1,312,000. The late starter has around $610,000.
Sit with that for a second. The early starter put in only $60,000 more over their life, yet finished with more than double the money. That extra decade at the start was worth more than all the years that followed, because it gave compounding the most precious thing it needs – time.
The lesson isn’t to feel bad if you’re not 25. It’s the opposite. It’s that the best day to start was years ago, and the second best is today. Every year you wait is a year of compounding you don’t get back.
Compound Interest Is Not a Special Account
Here’s a myth worth clearing up, because a lot of people go looking for the wrong thing.
Compound interest isn’t a magic account you open at a bank. Yes, savings accounts compound – but at today’s rates, the returns are usually small, and often don’t even keep up with rising prices. Parking your money there and expecting it to transform your life is like planting a seed in a dark cupboard and wondering why nothing grows.
The real power of compounding shows up when you invest. When you own shares or ETFs and reinvest the dividends and growth, your returns start earning returns of their own, and over years that’s where the snowball gets big. Historically, investing in a diversified mix of assets has compounded far faster than cash in the bank, though with more ups and downs along the way.
So compound interest isn’t somewhere you put your money. It’s a force you harness, mostly by learning how to start investing and giving it time.
How to Put Compounding to Work
The good news is you don’t need to be clever to use compounding. You need to be patient and consistent. Here’s how.
- Start now, not later – You’ve seen what an extra decade does. The single biggest lever you have is the date you begin.
- Invest, don’t just save – Savings are safe but slow. To really compound, your money needs to be working in growth assets, as part of a plan that suits you.
- Reinvest what you earn – When you take your dividends or returns and put them straight back in, you’re pouring fuel on the fire. Spend them, and the snowball stops growing.
- Add to it regularly – Small, steady amounts added over time stack up with the compounding to build something far bigger than the sum of what you put in. Learning to find the surplus each month is what makes this possible.
- Then leave it alone – This is the hard part. Compounding needs time and patience, so the goal is to set it up and let it run, not to tinker every time the market wobbles.
Do those five things and you’ve built a quiet wealth machine. It’s not flashy, but it’s how most real financial independence is actually built.
The One Thing That Kills Compounding
If time is compounding’s best friend, interruption is its enemy.
Every time you pull your money out, stop investing for a while, or panic-sell in a dip and sit on the sidelines, you reset the snowball to the bottom of the hill. High fees do a quieter version of the same thing, skimming a little off your returns every year so there’s less to compound.
The investors who win with compounding aren’t the smartest. They’re the ones who started early, kept going, and left it alone long enough for the magic to show up. If you’d like a hand building a plan you can actually stick with, that’s what financial coaching is for.
In Summary
Compound interest is earning returns on your returns, and it’s the closest thing to magic in money – a snowball that’s slow at first and spectacular later.
It rewards time above all, which is why starting early beats starting big, and why the worst thing you can do is wait. It isn’t a special bank account, it’s a force you harness by investing, reinvesting, adding regularly, and then having the patience to leave it alone.
You don’t need a fortune or a finance degree to use it. You need to start, and then let time do the work it’s so good at.
If you could go back and give your younger self one piece of money advice, what would it be? Let me know in the comments below.
P.S. Compounding can only work on the money you free up to invest. Grab my free Wealth Tracker to find that surplus – the sooner you put it to work, the longer the snowball has to roll.
Yes, Andrew, if only more people understood and did this.
Thankyou for the post.
Simone