ETFs have become one of the most popular ways for everyday Australians to invest, and for good reason.
They sound technical, but the idea behind them is genuinely simple – and once it clicks, a lot of investing feels less intimidating.
In this post we’ll look at what an ETF actually is, how it works, why so many people use them, the downsides worth knowing, and how to think about whether they fit your plan.
The growth in ETFs in 2026 has been the largest in history, people are seeing the benefits of having them as a base in their portfolio.
What Is an ETF?
ETF stands for exchange traded fund. Let’s take that name apart, because it explains the whole thing.
A “fund” is simply a bucket that holds lots of different investments at once. “Exchange traded” means you can buy and sell that bucket on the stock exchange, just like you’d buy a single share.
So an ETF is a ready-made bundle of many investments – often hundreds of companies – that you can buy in one go, with one click, for one price.
Think of it like a fruit basket instead of a single apple. Rather than buying one company’s shares and hoping that company does well, you buy a basket that already holds a slice of hundreds of them.
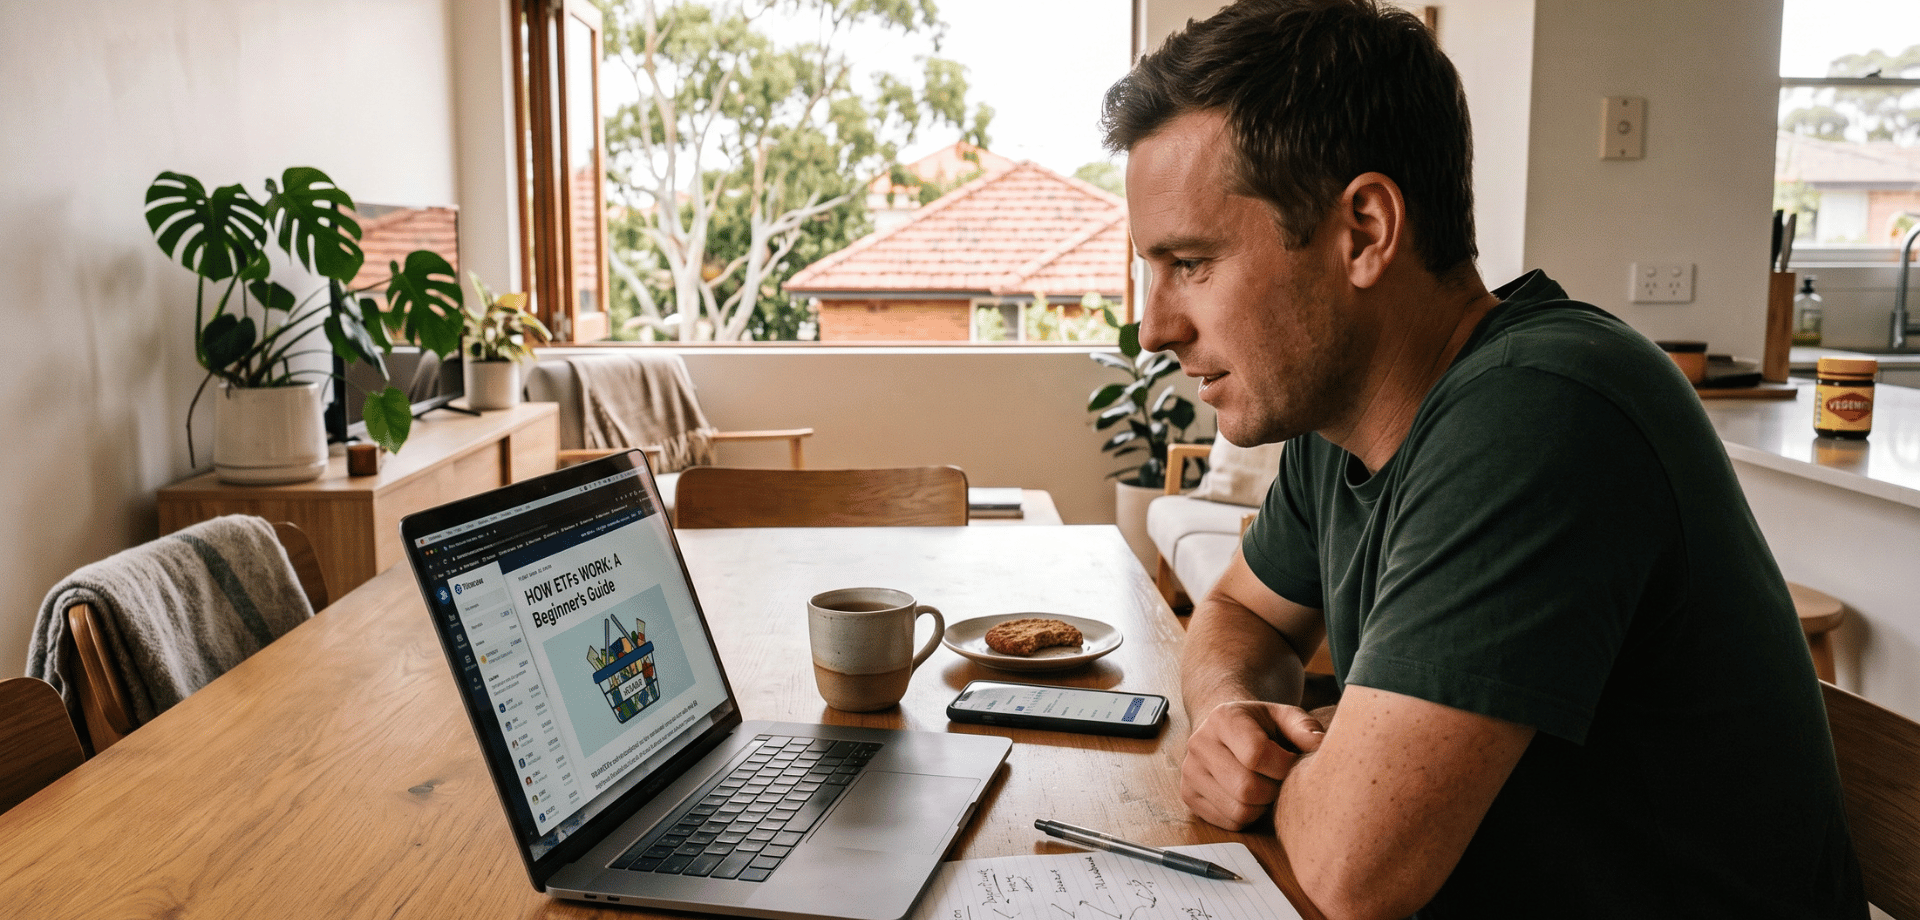
How ETFs Actually Work
The most popular ETFs are built to track an index. An index is just a list that measures a slice of the market – for example, the 200 largest companies on the Australian share market, or 500 of the largest in the United States.
When you buy a unit of an index ETF, your money is spread across every company on that list, in proportion. If the overall list goes up, your ETF goes up. If it goes down, so does your ETF.
Along the way, many ETFs also pay you distributions – your share of the dividends the underlying companies pay out. You can take that as income, or reinvest it so it adds to your compounding over time.
That’s really it. You’re buying a small piece of a whole market, in a single, tradeable parcel.
Why So Many People Use ETFs
ETFs have taken off because they solve a few problems that used to make investing hard for ordinary people.
- Instant diversification – One purchase spreads your money across hundreds of companies, which is the heart of spreading your risk. If one company stumbles, it’s a tiny part of the basket.
- Low cost – ETFs usually charge a small annual fee, often well under half a percent, where older-style managed funds can charge several times that. Over decades, lower fees leave more in your pocket.
- Simple and hands-off – You don’t have to research and pick individual winners. You buy the basket and get the market’s overall return.
- Accessible – You can start with relatively small amounts and add to them regularly, rather than needing a big lump sum.
- Transparent – You can see exactly what an ETF holds, so there are no nasty surprises about where your money is.
For someone who wants to start investing in shares without becoming a full-time stock picker, that combination is hard to beat.
The Downsides Worth Knowing
ETFs are useful, but they’re not magic, and anyone who tells you an investment has no downside is selling something. Here’s the honest other side.
- They still rise and fall – An ETF follows its market, so when the market drops, your ETF drops with it. They spread risk, they don’t remove it.
- You get the average, not the winner – By owning the whole basket, you’ll never beat the market, because you are the market. For most people that’s a feature, but it’s worth understanding.
- Not all ETFs are broad and simple – Some are narrow, focused on a single country, sector or theme, and can be far more volatile. The word “ETF” alone doesn’t mean “safe and diversified”.
- You still have to choose – There are hundreds of ETFs, and picking which ones suit your goals and risk still takes a bit of learning.
None of these are reasons to avoid ETFs. They’re just reasons to go in with your eyes open.
ETFs vs Shares vs Managed Funds
It helps to see where ETFs sit compared to the main alternatives.
- Individual shares – You pick single companies yourself. More control and more potential upside, but more risk and more work, and it’s easy to get burned if you’re new to it.
- Managed funds – A professional picks the investments for you, inside a fund. Convenient, but often with higher fees, and the performance doesn’t always justify them. A lot of people who’ve had a poor experience here are drawn to ETFs as a simpler, cheaper alternative.
- ETFs – A middle path. You get a professionally built, diversified basket like a managed fund, but at a low cost and with the simplicity of buying a single share.
There’s no single right answer, and plenty of people use a mix of all three. The point is to understand the trade-offs rather than follow a tip.
How to Think About ETFs in Your Plan
I’m a coach and educator, not a licensed adviser, so I won’t tell you which ETF to buy. But here’s how I’d encourage you to think about them.
Treat an ETF as a tool, not a strategy. A broad, low-cost index ETF can be a simple core to build around, but it still sits inside a bigger plan – your goals, your timeframe, and a sensible mix across more than one asset class.
Then the ordinary rules apply. Invest regularly rather than trying to time the market, think in years rather than weeks, and let your returns compound. If you’re just getting going, my guide on how to start investing walks through the first steps, and if you’d value a hand building a plan that’s right for you, that’s what financial coaching is for.
For the specifics of what suits your situation and the tax side of distributions, it’s worth getting advice. The concept is simple, but your circumstances are your own.
In Summary
An ETF is a low-cost, ready-made basket of many investments that you can buy and sell like a single share. In one purchase, you get instant diversification, which is why so many Australians use them to build wealth.
They’re simple, cheap and transparent, but they still rise and fall with the market, and not every ETF is a broad, safe one. Used well, as part of a diversified long-term plan, they’re one of the easiest ways for an ordinary person to own a slice of the market.
Have you started using ETFs yet, or is choosing between them the thing holding you back?
P.S. Before you pick any investment, it helps to know how much you’ve got spare to put to work. Grab my free Wealth Tracker to see where your money goes – the surplus you find is what you can start investing.